Best Money Apps for Homeowners Managing Insurance Costs (2026)
Insurance premiums, deductibles and repair bills arrive at awkward times. The best money apps can turn that chaos into a calm, predictable system. This guide shows homeowners and landlords how to use digital tools to budget for coverage, build a claims cushion and keep paperwork organised in 2026.
We focus on what the tools actually do, not brand hype. You will see which features matter, how to set them up for property-related costs and where each type of app tends to fall short.
Why Property Owners Need a Dedicated Money System
Owning property means irregular, lumpy expenses. A roof repair, an annual premium or a deductible after storm damage can cost more than a month of salary. Without a plan, these bills land on credit cards and quietly turn into long-term debt.
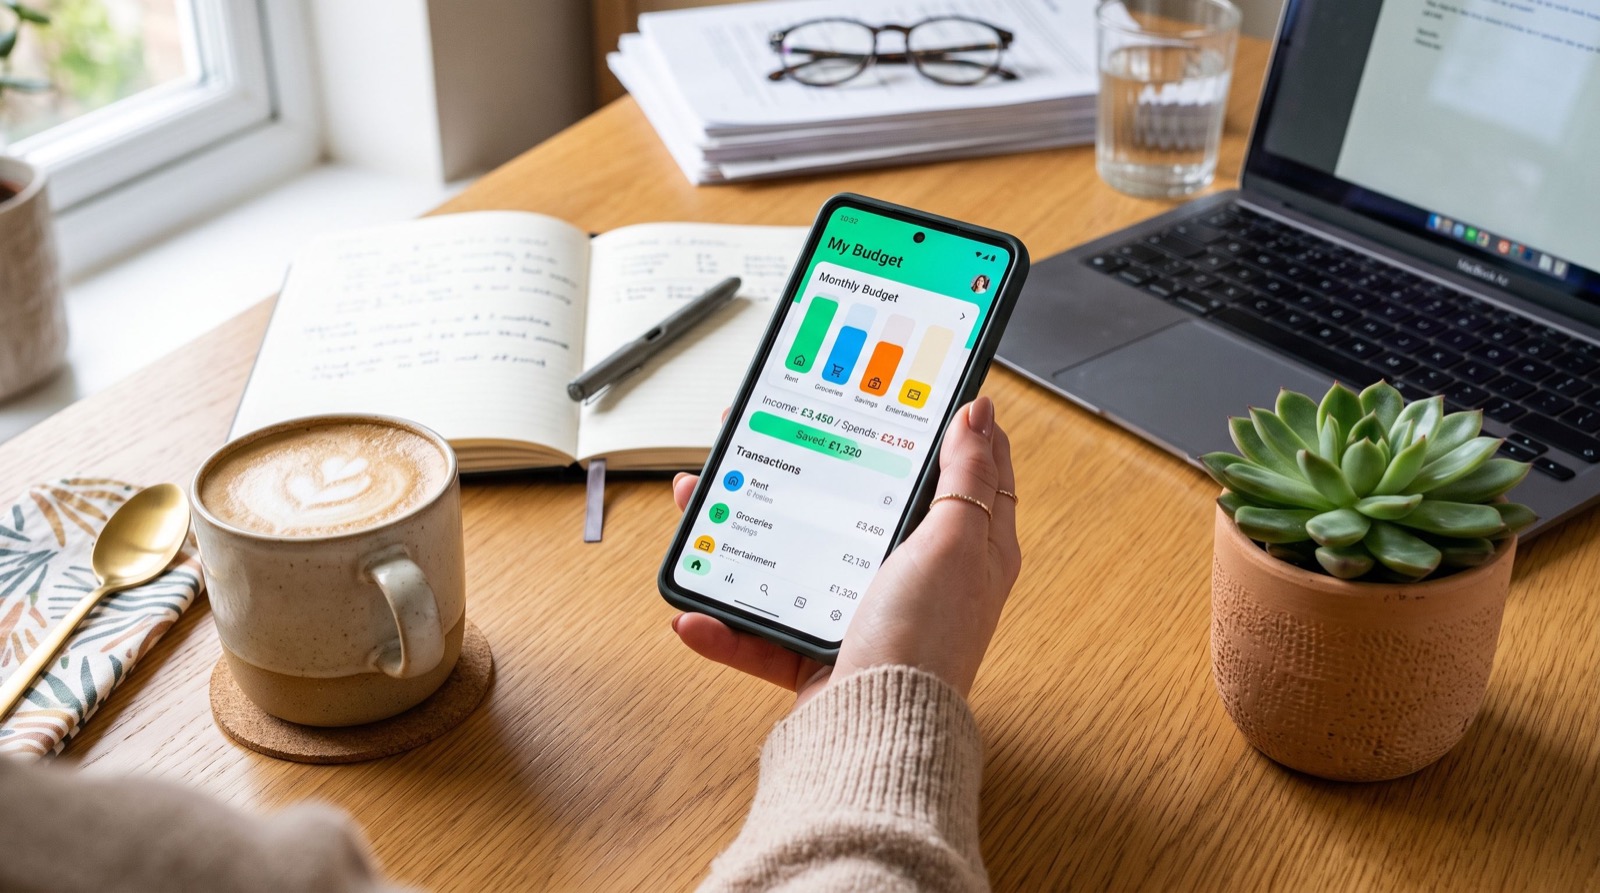
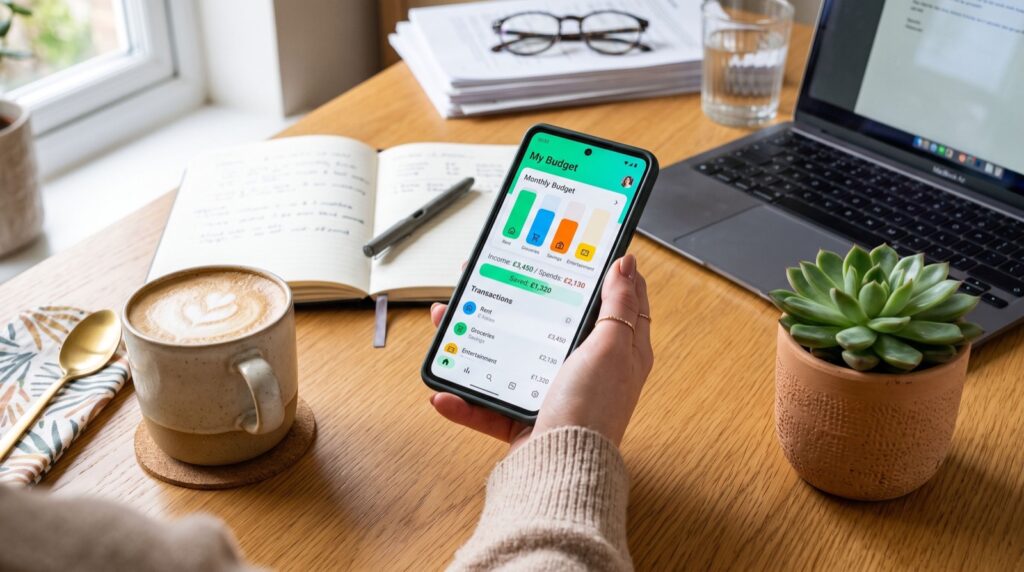
A good app does three jobs. It shows where money goes, it sets cash aside for known future costs and it keeps records you can pull up during a claim. Think of it as a small back office for your home.
The costs most owners underestimate
- Annual or semi-annual insurance premiums paid in one lump sum.
- Deductibles, which can reach several percent of the home’s value for storm or flood cover.
- Routine maintenance such as plumbing, wiring and pest control.
- Temporary housing if a covered event makes the property unliveable.
What Makes the Best Money Apps Worth Using
Features vary widely, so judge each app against your goals rather than its star rating. For property owners, five capabilities matter most.
- Sinking funds or goal buckets to set aside money for premiums and repairs.
- Bill reminders that warn you before renewal dates.
- Receipt and document storage for claims evidence.
- Clear fee disclosure with no surprise monthly charges.
- Bank-grade security including two-factor authentication.
Comparing Types of Money Apps for Home Costs
| App type | Strength | Weakness | Good for |
|---|---|---|---|
| Budgeting trackers | Detailed categories and reports | Manual set-up effort | Planners who enjoy data |
| Digital wallets | Fast transfers and splitting | Limited long-term saving tools | Shared household costs |
| Savings automation apps | Hands-free transfers | Fewer spending insights | Building a deductible fund |
| Net worth dashboards | Whole-picture view of assets | Can feel overwhelming | Owners with several properties |
Most owners end up combining two types. A savings automation app handles the “set aside” job, while a tracker or wallet handles the day-to-day flow.
Which is the best money app for a deductible fund?
The one that makes saving automatic and keeps funds at an insured institution. Look for a separate, named bucket such as “Deductible Reserve” so the money is clearly earmarked and harder to spend by accident.
How to Build a Deductible and Repair Reserve
Start by reading your policy. Find the deductible for each type of event, because wind, water and fire often differ. Then pick a target equal to your highest realistic deductible plus a small maintenance buffer.
Next, divide that target by the number of months you want to take to reach it. For example, a 150,000 reserve over 15 months means 10,000 a month. Automate the transfer for the day after payday and treat it like a bill.
A practical setup for one property
- Bucket one: insurance premium, funded monthly so renewal day is painless.
- Bucket two: deductible reserve, funded until the target is reached.
- Bucket three: maintenance, funded at about 1 percent of property value per year.
When the premium bucket is full, the bill simply drains it. No stress, no card balance.
Keeping Records That Strengthen a Claim
Insurers want proof. The Insurance Information Institute recommends keeping a home inventory so you can document belongings quickly after a loss; see its home inventory guide for a clear walkthrough.
Use your app’s document folder, or a linked cloud drive, to store photos, receipts, appraisals and policy PDFs. Update the folder twice a year. A five-minute habit can save weeks of arguments later.
Money Habits That Lower Your Long-Term Costs
Apps are only as helpful as the habits behind them. Pair your tools with sound routines, and many of the personal finance tips that work for everyday budgeting translate directly to property ownership: pay yourself first, review subscriptions monthly and keep emergency cash separate.
A few property-specific habits also help:
- Shop your policy every year rather than auto-renewing.
- Bundle policies only when the bundle actually saves money.
- Raise your deductible if your reserve can safely cover it.
- Invest in prevention such as leak sensors, wiring checks and secure locks.
When You Need Professionals, Not Just Apps
An app can show you the numbers, but it cannot inspect a roof or negotiate with an adjuster. For repairs, valuations and renewals, work with quality service providers who offer written quotes, references and clear timelines.
Ask every provider the same four questions. What is included? What is excluded? How long will it take? What happens if something goes wrong? Record the answers in your app so you can compare later.
Security Checklist Before You Link Accounts
- Turn on two-factor authentication for every financial app.
- Use a unique password stored in a password manager.
- Confirm the app is read-only for budgeting features where possible.
- Review connected accounts every quarter and remove any you no longer use.
- Never share one-time codes, even with someone claiming to be support.
Frequently Asked Questions
What are the best money apps for tracking home expenses?
Choose a budgeting tracker for detailed categories and a savings automation app for hands-free reserves. Many owners use both, so each tool does one job well.
How much should I keep in a deductible reserve?
Aim for at least your largest realistic deductible. If your policy has a percentage deductible for storms or floods, calculate it from your home’s insured value and fund that number.
Are money apps safe for storing insurance documents?
Many are, provided they use encryption and two-factor login. For extra safety, keep a second copy in a separate encrypted cloud folder and an offline backup.
Do money apps replace a financial advisor?
No. Apps organise and automate, but an advisor or licensed insurance agent can tailor coverage and strategy to your situation.
Bottom Line
The best money apps do not make you richer overnight. They make costs visible, savings automatic and records easy to find. Set up three buckets, store your documents, review everything twice a year and your 2026 insurance and repair costs will feel far more manageable.